n% Rule
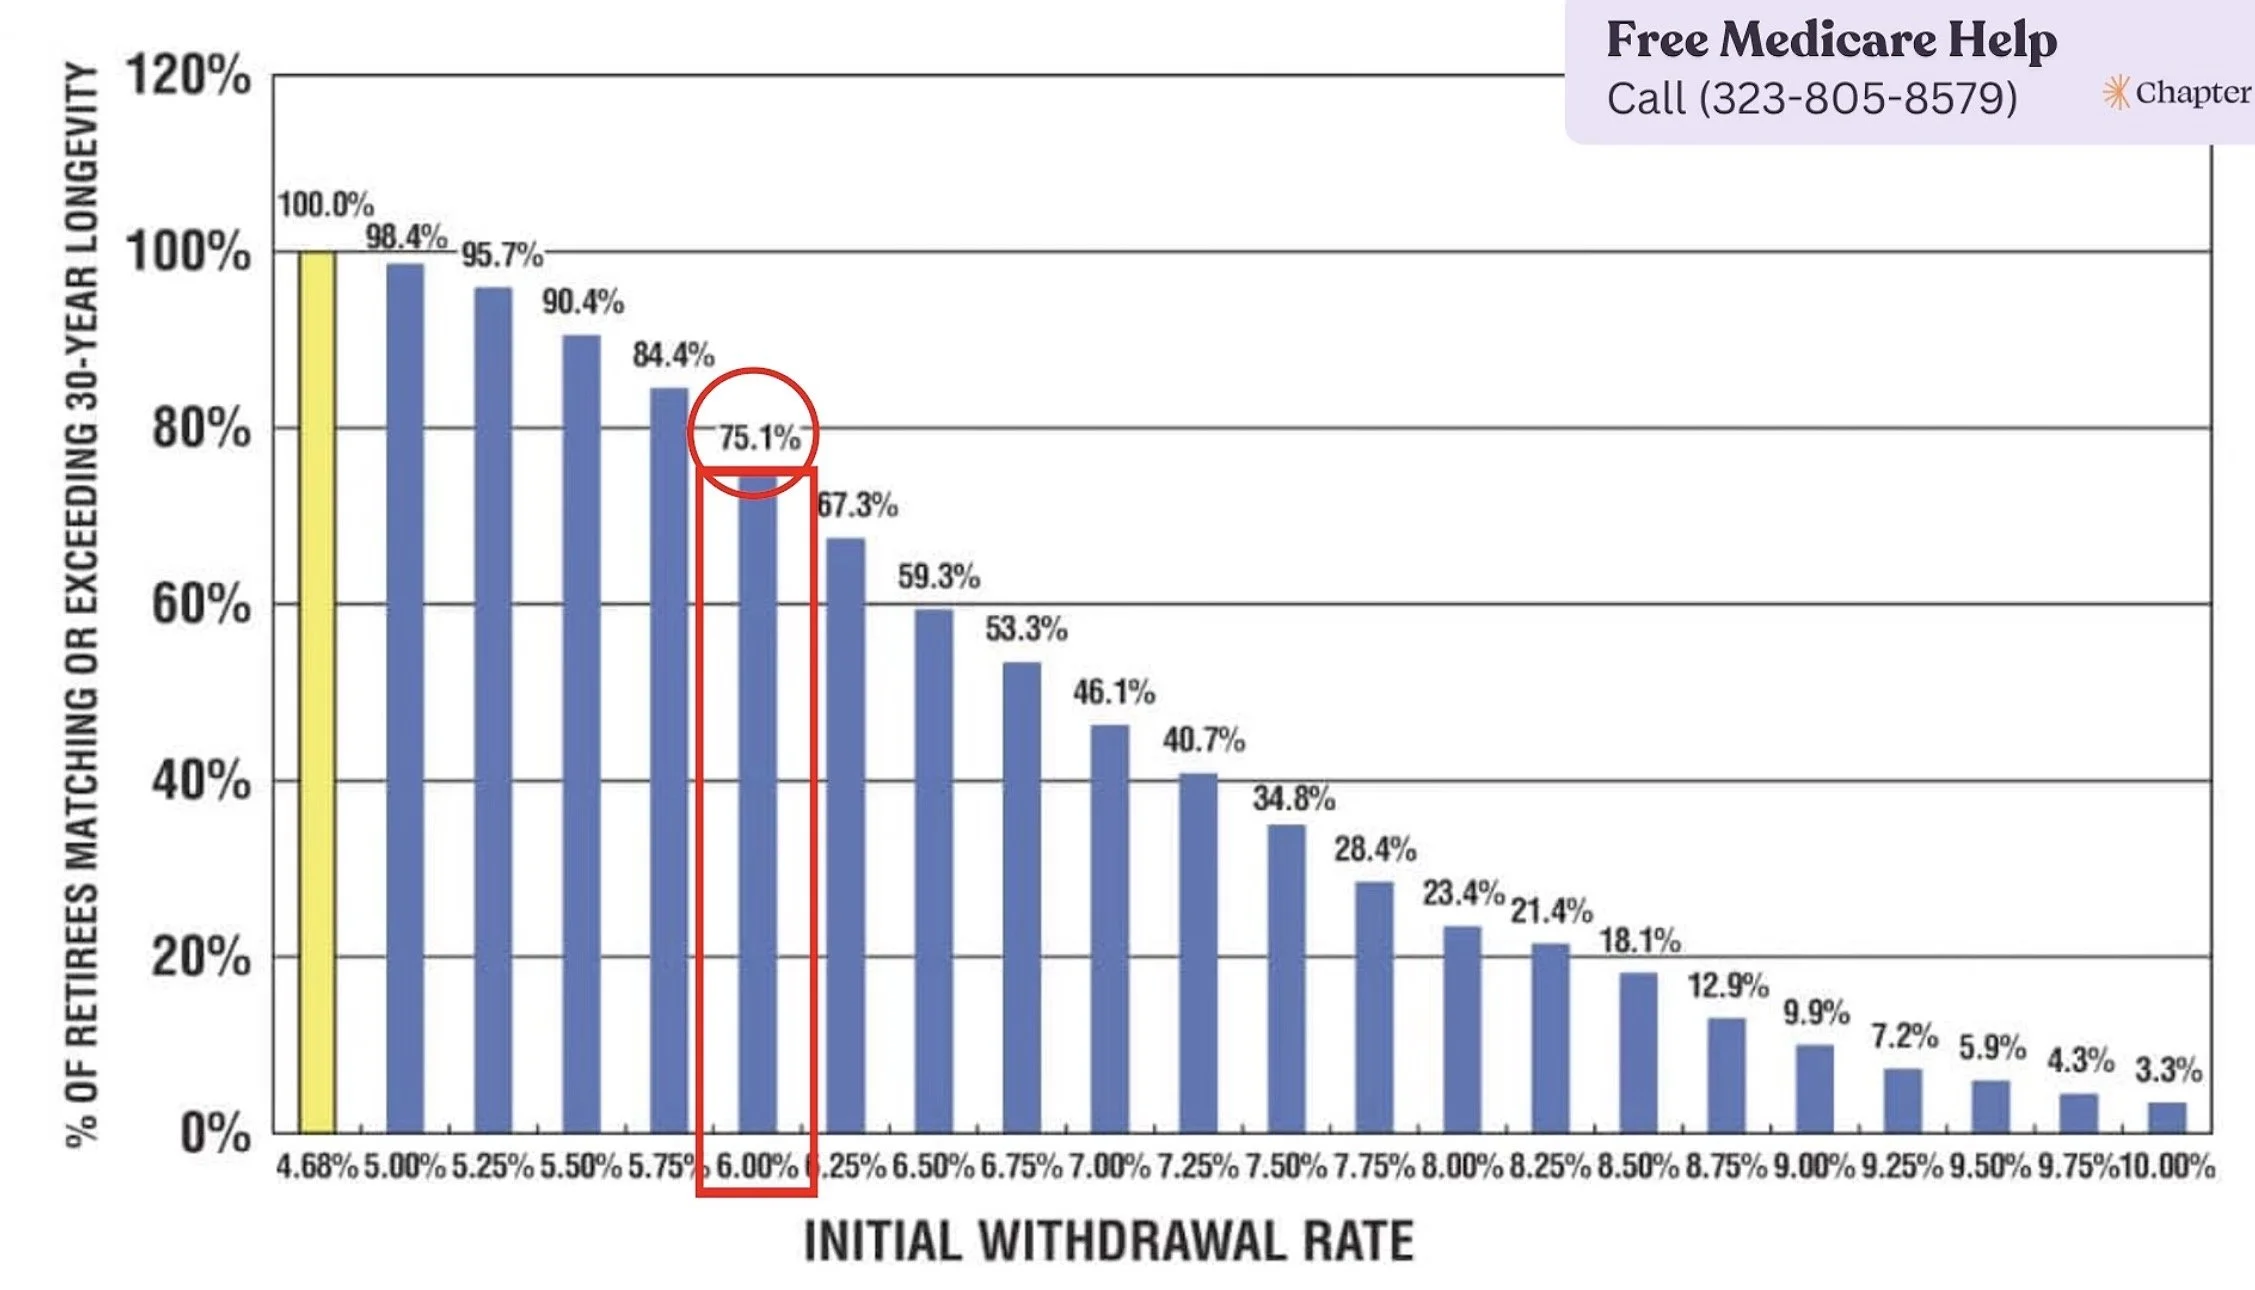
William Bengen updated his classic retirement benchmark to a 4.7% Safe Initial Withdrawal Rate (and up to 5% with optimized diversification) for a 30-year retirement. (Assumes 0% failure if constantly drawing 4.7% annually).
Asset Allocation: Shifts to roughly 55% stocks, 40% bonds, and 5% cash (or equivalents).
Worst-Case Origin: The 4.7% rate still protects against absolute worst-case historical market crashes (like the high-inflation bear market of 1968).
Below is one highlight that 75% failure implies “making financial adjustments” for a given year less than 6%, in ¼ of those years.